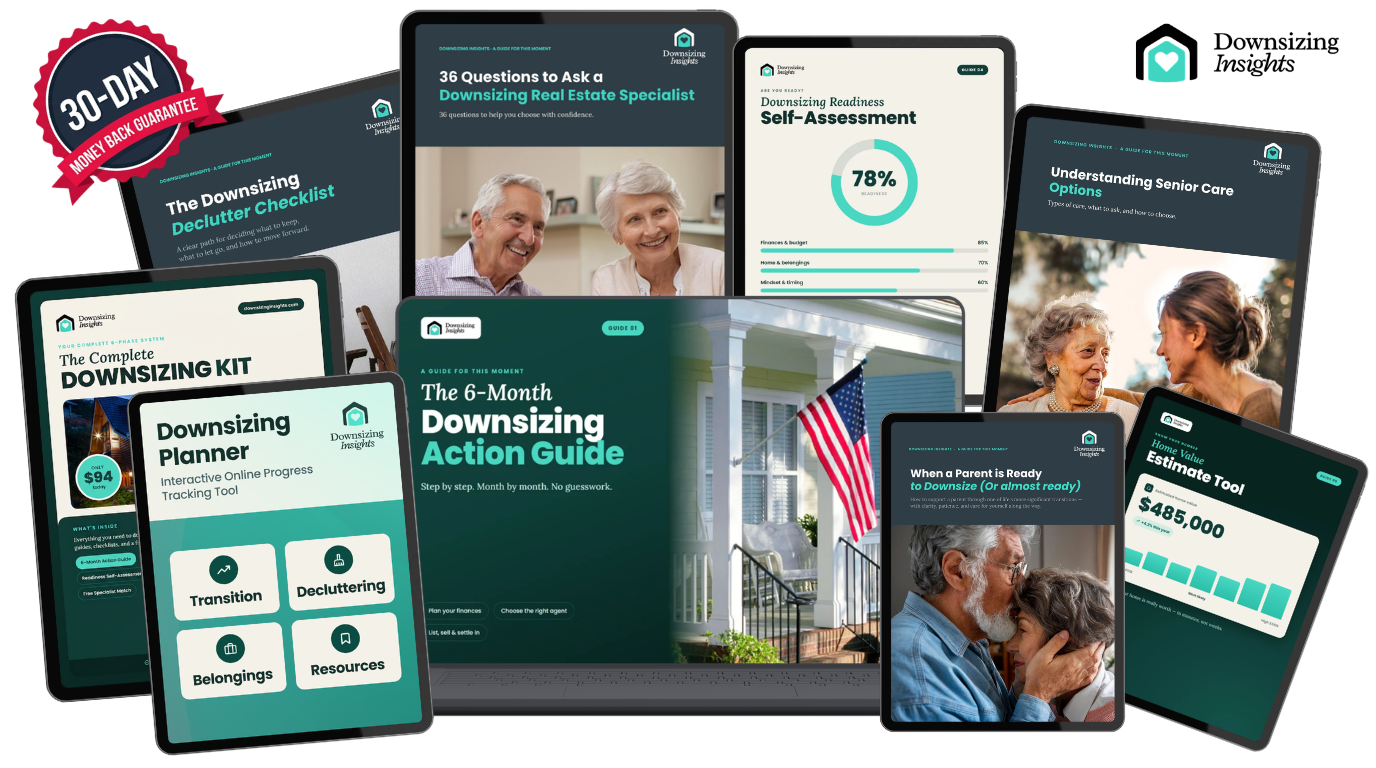
This page covers the local picture. The Complete Downsizing Kit covers the rest: six guides, one clear sequence, from finances to the final move. $94 for instant access.
If you have been thinking about downsizing in New York City, you are probably not close to making a decision yet. You may have started noticing things: the second bedroom that no one sleeps in, the co-op maintenance bill that keeps climbing, the walk-up stairs that feel different at 68 than they did at 48. Or maybe an adult child has raised the subject, and you are not sure how you feel about it.
That is a normal place to be. Most people who eventually downsize in New York spend a year or more in that early thinking stage before anything actually happens. This page is written for that stage. It covers what downsizing tends to look like in New York City specifically, what it costs, how New York State taxes affect the math, and where people actually end up. None of it requires a timeline.
What downsizing usually looks like in New York City
Downsizing in New York starts inside a very particular kind of home. In Manhattan, it is often a prewar co-op bought decades ago, a two- or three-bedroom with high ceilings, aging plumbing, and a monthly maintenance charge that has doubled since the mortgage was paid off. In Brooklyn, it might be a brownstone in Park Slope or Bay Ridge that housed a family of four and now holds one or two people and thirty years of accumulated belongings. In Queens, Staten Island, or the Bronx, the profile shifts toward single-family houses on modest lots, many built in the 1950s through 1970s, with basements full of storage and yards that require weekend attention.
These homes share a few things. They were designed for a bigger household. Their systems, boilers, wiring, roofing, are aging alongside the people living in them. And they carry costs, both in money and in physical effort, that made sense during a different chapter of life.
New York City is home to roughly 1.43 million residents aged 65 and older, a figure that grew 53 percent over the past two decades. That population is concentrated in neighborhoods where long-term homeownership is most common: eastern Queens, southern Brooklyn, parts of the Bronx, and Staten Island's mid-island corridors. The median home sale price in the city hovers around $900,000 as of mid-2026, though that figure masks enormous variation. A co-op in Riverdale and a brownstone in Carroll Gardens occupy very different price universes, and both differ sharply from a ranch house in Tottenville.
"Smaller" in New York does not always mean cheaper. A one-bedroom in a well-located elevator building can carry a higher price per square foot than the three-bedroom being left behind. For most people considering this transition, "smaller" means something in the range of 600 to 1,000 square feet, a real drop from the 1,500 to 2,500 square feet many long-held homes offer.
What tends to prompt the decision here
Three factors show up most often when New Yorkers begin thinking seriously about a smaller home.
The first is empty nesting. Once children leave for their own apartments or move out of the city entirely, the extra bedrooms stop serving their original purpose. Cleaning takes longer than it needs to, and the space begins to feel like something being maintained rather than lived in.
The second is cost. Co-op maintenance fees, property taxes on an outer-borough house, utility bills on an older building, and the steady need for repairs all tend to climb faster than a fixed retirement income. For some, downsizing is less about wanting a different lifestyle and more about wanting the household budget to work again.
The third is physical reality. Stairs are often the specific thing that shifts the conversation from theoretical to urgent. A fourth-floor walk-up that felt routine at 50 can feel precarious at 72, especially carrying groceries or managing a knee that did not used to be a factor. Houses with second-floor primary bedrooms raise the same concern in a different form.
Many people describe these factors building gradually rather than arriving all at once. The thought tends to sit in the background for months or years before it turns into a plan.
Where people in New York City tend to move
When New Yorkers do decide to downsize, the paths they take fall into four broad categories. None of them is inherently better than the others. Each involves a different set of tradeoffs in cost, independence, community, and proximity to the life someone has built.
Staying in the city, smaller
The most common first instinct is to stay nearby. Someone leaving a large co-op on the Upper West Side might look for a one-bedroom in the same neighborhood, ideally in an elevator building with a doorman. A homeowner in Bay Ridge might consider a condo in Bensonhurst or Sunset Park. The appeal is straightforward: same doctors, same friends, same grocery store, same subway line. The tradeoff is that in-city one-bedrooms in elevator buildings often cost more per square foot than the larger home being left, and the supply of accessible, well-maintained smaller units in popular neighborhoods tends to be tight.
Suburbs and nearby towns
Westchester, Long Island, and northern New Jersey absorb a significant share of New York City downsizers. The appeal is more space for less money, car access, and quieter streets. The honest tradeoff is that daily life becomes car-dependent in most of these areas, which matters more as driving becomes less comfortable over time. For someone whose adult children live in Westchester or on Long Island, proximity to family often settles the question.
55+ and active adult communities
The New York metro area has a meaningful inventory of age-restricted communities, concentrated on Long Island and in Westchester and Putnam counties. On Long Island, communities like Meadowbrook Pointe in Westbury, Country Pointe Plainview, and The Greens at Half Hollow in Melville offer condo and townhome living with resort-style amenities and HOA-managed maintenance. Prices for resale units in these communities generally range from roughly $750,000 to over $1 million, with monthly common charges running $500 to $1,000 depending on the community and unit type. In Westchester, communities like Heritage Hills in Somers and newer developments in Cortlandt Manor and Yorktown serve a similar market at somewhat lower price points.
These communities remove yard work and exterior maintenance from the equation entirely. The tradeoff is that monthly fees are a permanent fixture, and the social environment is structured in a way that appeals to some and feels constraining to others.
Leaving the area
The most common reason New Yorkers leave the metro entirely when downsizing is proximity to adult children or grandchildren who have settled elsewhere. Florida, the Carolinas, and parts of New Jersey outside commuting range are frequent destinations. Lower cost of living is often part of the calculus, but most people who leave describe family as the primary pull. The adjustment involves leaving behind a network of neighbors, routines, and medical providers built over decades, which is a real cost even when it does not show up on a spreadsheet.
What the New York City market means for timing
New York City's market for smaller units has stayed relatively stable in recent years, without the sharp seasonal swings common in suburban markets. One-bedroom apartments and condos in Manhattan and Brooklyn tend to see consistent demand from a broad pool of buyers, which means sellers are not usually waiting for a narrow window to list. Across the city, the median home sale price rose roughly 5 percent year over year through mid-2026, and homes in the median range are typically selling within about 60 to 70 days.
Spring and early fall tend to bring more listings and more buyers into the market at the same time, which creates more options on the buy side and more competition on the sell side. Winter is typically quieter in both directions.
Market conditions are worth understanding as context. They are not a reason to move faster or slower than feels right. Most people's actual timing is set by something other than what the market is doing: a health change, a family conversation, or a moment when the idea finally shifts from theoretical to practical. If a current number for what the home is worth would help ground the thinking, a home value estimate is a reasonable place to start that conversation with yourself.
What the process costs on the sell side
Selling a home in New York City carries some of the highest transaction costs in the country, and the specifics catch many people off guard. The layers include state taxes, city taxes, building-level fees, and professional costs that vary depending on whether the property is a co-op, condo, or house.
| Cost item | Typical range |
|---|---|
| NYS real estate transfer tax | 0.4% of sale price (0.65% above $3M) |
| NYC Real Property Transfer Tax | 1% under $500K, 1.425% above $500K |
| Co-op flip tax (if applicable) | 1% to 3% of sale price, varies by building |
| Attorney fees | $2,000 to $4,000 |
| Moving costs (walk-up or co-op logistics) | $3,000 to $8,000+ |
| Home prep, cleaning, and minor repairs | $2,000 to $5,000 |
On a $900,000 co-op sale in Manhattan, the combined NYS and NYC transfer taxes alone come to roughly $16,000. Add a 2 percent flip tax and that figure jumps to $34,000 before broker commissions, legal fees, or any costs associated with preparing the unit for sale. Total seller closing costs in NYC, including commissions, commonly land in the range of 8 to 10 percent of the sale price.
The cost that surprises most people is what happens to belongings that do not fit in a smaller space. Selling furniture quickly, often at a steep discount, or paying for short-term storage while decisions get made, adds up in ways that rarely appear in the initial budget.
Property taxes and financial considerations in New York State
New York offers several property tax relief programs specifically for homeowners 65 and older, and these are among the most valuable and least widely known facts on this page.
The Senior Citizens Homeowners' Exemption, known as SCHE, can reduce the taxable assessed value of a primary residence by up to 50 percent. In New York City, the combined income limit for all owners is $58,399. The exemption covers one-, two-, and three-family homes, condominiums, and cooperative apartments. Homeowners who qualify for SCHE automatically receive the Enhanced STAR exemption as well. SCHE must be renewed every two years through the NYC Department of Finance, with applications typically due by March 15.
The STAR program, which stands for School Tax Relief, offers a separate reduction in the school-district portion of property taxes. Enhanced STAR, available to homeowners 65 and older, uses an income threshold of $110,750 for the 2026 to 2027 benefit year. Most new applicants receive this as a credit check from the state rather than a direct reduction on the tax bill, though homeowners who were enrolled under the older exemption system may still receive it that way.
Capital gains are the larger question for anyone who has owned a New York home for decades. The federal primary-residence exclusion allows up to $250,000 in gains to be excluded for a single filer, or $500,000 for a married couple filing jointly. For homes that have appreciated well beyond those thresholds, which is common across much of New York City, the remaining gain becomes taxable income at both the federal and state level.
New York State does not offer a preferential rate for long-term capital gains. Instead, it taxes gains as ordinary income under the state's progressive brackets, which range from 4 percent to 10.9 percent depending on total income. New York City residents pay an additional local income tax on top of the state rate, with a top rate of 3.876 percent. For a high-income seller, the combined federal, state, and city tax rate on gains above the exclusion can exceed 34 percent.
These rules change, and the specific numbers involved vary enormously from one household to the next. A conversation with a tax professional familiar with New York real estate is worth having well before a listing decision, not after.
The part that is harder to plan for
Leaving a home you have lived in for decades is not primarily a logistics problem. Many people underestimate the emotional weight of the transition until they are in the middle of it, sorting through a closet that holds forty years of family history and realizing the decision about what to keep is not really about the objects at all.
Couples and partners do not always arrive at readiness at the same time. One person may be ready to list while the other needs another year, and that gap can create real friction if it is not named directly. Adult children often carry their own attachment to a childhood home or specific pieces of furniture, and their opinions can add complexity even when they are offered with good intentions.
What tends to help most is time and honest conversation. Naming the difficulty plainly, rather than rushing past it in favor of logistics, usually makes the practical steps easier when they do arrive. The Downsizing Readiness Self-Assessment can help surface where you and your family actually stand, without any pass-fail score attached.
What to do with everything in the house
Sorting through belongings in a New York City home has its own dynamics. Space constraints mean that accumulation tends to be dense rather than spread out, so what looks like a modest closet or storage unit often holds more than expected once the sorting begins. A realistic timeline for a full sort is four to eight weeks of steady work for a three-bedroom apartment, longer for a house with a basement or attic.
Adult children typically want a small number of specific items, a piece of jewelry, a set of photographs, perhaps one piece of furniture with particular meaning. The volume of what remains usually surprises everyone.
Several paths exist for what does not make the move. Estate sale companies operating in the city can handle a unit with substantial furniture and decorative items. Consignment works for individual higher-value pieces. Donation organizations like Housing Works, the Salvation Army, and Habitat for Humanity ReStore offer pickup service for usable household goods. Junk removal services handle whatever remains after everything else has been sorted. Most downsizing projects in New York end up using more than one of these options at the same time. The Family Downsizing Planner can help track what goes where, room by room, as the sorting progresses.
Clearing out a home before listing it, rather than after, tends to make the sale itself go faster. Buyers in New York respond noticeably better to apartments and houses that already feel open and unburdened.
Kinds of help available in New York City
New York City has a deeper bench of senior-focused professionals than most markets, largely because the volume of transitions here supports specialization. Understanding what each type of professional actually does can help in deciding whether any of them make sense for a particular situation.
Senior Move Managers coordinate the physical side of a move: sorting, packing, working with movers, and setting up the new home. The National Association of Senior and Specialty Move Managers lists several members serving the five boroughs, including Paper Moon Moves in Brooklyn (NASMM A+ Accredited), SAMMS in Great Neck serving all five boroughs, A Nu Start NY in Manhasset covering Nassau, Queens, Manhattan, and Brooklyn, and Urban Clarity in Brooklyn. NYC moves involve specific logistics that general movers may not anticipate: elevator reservation windows, certificates of insurance required by co-op boards, narrow hallways, and building-specific move-in rules. A move manager familiar with these requirements can prevent delays that add cost.
Real estate agents who hold the Seniors Real Estate Specialist designation have specific training in the financial and emotional considerations that come up when older adults sell a longtime home. That training matters in a market as complex as New York's co-op and condo system, where board approval processes, flip taxes, and building financials all affect the transaction. You may find it helpful to speak with an agent who has handled senior transitions in your specific neighborhood and building type.
Professional organizers offer a narrower kind of help, focused on the sorting and decision-making process rather than the move itself. This can be useful before any listing decision has been made, when the goal is clarity rather than logistics. Estate attorneys and tax professionals round out the picture, each handling one specific piece of a process that, in New York, tends to involve more legal and financial layers than in most other cities.
Common questions about downsizing here
How long does downsizing usually take in New York City?
Most people find the process takes between four and eight months from the first serious sorting session to moving day. Co-op sales tend to take longer than condo or house sales because of the board approval process, which commonly adds six to ten weeks to the timeline after a buyer is found.
How much does it cost to sell a home in New York City?
Total seller closing costs in New York City typically run 8 to 10 percent of the sale price when broker commissions are included, or roughly 2 to 4 percent excluding commissions. The combined NYS and NYC transfer taxes alone amount to 1.4 to 2.075 percent, and co-op sellers often face an additional flip tax of 1 to 3 percent set by the building.
What property tax relief is available for seniors in New York?
New York City offers the Senior Citizens Homeowners' Exemption (SCHE), which can reduce the taxable assessed value by up to 50 percent for homeowners 65 and older with combined income under $58,399. Qualifying for SCHE also automatically enrolls you in Enhanced STAR. The STAR program itself offers a separate school tax reduction with an income limit of $110,750 for 2026 to 2027. Both programs require application through the NYC Department of Finance or the state, and eligibility rules can change year to year.
Where do most people in New York City move when they downsize?
The most common paths are: a smaller apartment in the same or a nearby neighborhood (especially if elevator access is a priority), a suburb in Westchester or Long Island, a 55+ community like Meadowbrook Pointe or Heritage Hills, or an out-of-state move to be closer to adult children. The right choice depends almost entirely on what a person values most at this stage of life.
What happens to my capital gains if I have owned my home for decades?
The federal exclusion shelters up to $250,000 in gains for a single filer or $500,000 for a married couple filing jointly. Gains above that threshold are taxed as income at both the federal and state level. New York State taxes capital gains at ordinary income rates up to 10.9 percent, and New York City adds a local rate up to 3.876 percent. A tax professional can help model the specific numbers before a sale.
Do I need to sell before finding a new place?
There is no single right order. Some people prefer to secure their next home first, while others sell first to avoid carrying two sets of costs. Bridge loans and short-term rentals can cover the gap for those who sell before finding the right next place. In a co-op sale, the board approval timeline sometimes makes this sequencing more predictable than it would be otherwise.
How do I help a parent who is not ready to leave their home?
This is common, and it is rarely something that can be resolved with a logistics plan. Starting with small, low-pressure conversations about how the home is working day to day tends to go further than presenting a full moving proposal. Supporting a parent through this process works better when the final timing stays in their hands rather than being set by someone else's calendar.
What should I do with furniture that will not fit in a smaller apartment?
Consignment, estate sales, donation pickup services, and local resale platforms all work for different categories of items. Accepting some loss in value is realistic. Not everything can or should make the move, and starting the sorting process before listing tends to reduce both the financial and emotional cost of dealing with belongings under time pressure.
Where to start
None of this requires a decision today. If you are at the beginning of thinking about downsizing in New York, a reasonable first step might be having one honest conversation with a partner or adult child about how the current home is actually working, without any commitment beyond that conversation.
If a current number for what the home is worth would help ground the thinking, a home value estimate is a practical place to begin. It does not obligate anyone to anything. It is simply a number to plan around, and most people find that having it makes the rest of the picture clearer, even if nothing happens for another year.
Downsizing Insights offers a free checklist and planning resources built for this early stage, when the goal is understanding what the decision would actually involve rather than committing to a timeline. The guide to finding a senior-focused real estate agent covers what to look for in professional support and when it tends to be most useful.
Take your next step forward
You've learned the essentials. Now get the tools to move with confidence and clarity.